


 nova página do texto(beta)
 Inglês (pdf)
 Artigo em XML
 Referências do artigo

 Tradução automática
 Enviar este artigo por email
 Citado por SciELO
 Similares em
SciELO

 Permalink

1. Introduction
Pension systems have multiple objectives, including providing insurance against the risk of outliving one’s savings and smoothing income over the life cycle. Governments may also aim to reduce poverty among the old and pursue redistributive objectives (Barr and Diamond, 2010; Holzmann and Hinz, 2005).
From the insured’s perspective, social security serves as a means of saving during their working years in exchange for income during retirement. Research has shown that people frequently fail to save adequately for their old age (Banks et al., 1998; Moore and Mitchell, 1997). Thus, retirement income derived from social security is critical for sustaining a satisfactory standard of living.
Recent evidence suggests that mandatory contribution increases are more effective in increasing pension savings than measures that induce individuals to save more (Chetty et al., 2014). This phenomenon may be due to short-sightedness, a desire for late retirement, unexpected longevity, low valuation of the future, or insufficient income during the working period. A pension system that includes transfers and deferred income can be justified beyond governments’ specific goals regarding income distribution and poverty reduction.
However, the type of pension system implemented can have significant implications for intra- and inter-generational redistribution. Different systems can result in varying outcomes regarding risk distribution, access conditions, benefit amounts, duration, and financing. While a defined benefit system can be viewed as more redistributive than a defined contribution system, it typically comes with more stringent access restrictions. This can disadvantage vulnerable workers who may encounter difficulties with access or continuity in the formal labor market (Forteza and Rossi, 2013). On the other hand, defined contribution systems generally have less severe access conditions, but if not supplemented, they may provide meager benefits.
Irrespective of the organizational structure and regulations of a pension system, gender and socioeconomic status can create differences in benefits, including the age of benefit acquisition, duration, and amount. In Uruguay and throughout Latin America, low-income workers and women face challenges in fulfilling the requirements to access contributory pensions due to their low contribution densities (Lagomarsino and Lanzilotta, 2004; Forteza et al., 2009; Bucheli et al., 2010; Apella et al., 2011; Lavalleja et al., 2019). Moreover, there is a positive correlation between socioeconomic status and life expectancy (Case and Deaton, 2017; Bosworth, 2018). Consequently, higher-income individuals are more likely to receive benefits for more extended periods than lower-income individuals, which can adversely impact the system’s inequality. The distributive impact of a pension system is the outcome of the interplay between the program’s design and the contributors’ profile. Thus, analyzing the system requires specific methodologies grounded on various assumptions.
Constructing a counterfactual scenario that reflects the income people would have earned if the program did not exist is one of the primary methodological challenges of distributive impact analysis. Forteza (2018) proposes life cycle models to address pension system challenges. Income associated with the pension program is the flow of pension wealth returns. Therefore, social security contributions should be considered investments. The program’s impact should be identified as the difference between the absence return on social security contributions and voluntary savings and the return on voluntary savings in the pension program. We present a practical application of this model, providing a novel approach to analyzing public policy distributive impact.
Section 2 outlines the main characteristics of the Uruguayan social security system. Next, in section 3, the various methodological alternatives for estimating the distributive impact of pensions are discussed. In section 4 a simulation exercise is presented for the Uruguayan case using the methodology proposed by Forteza (2018) to estimate the distributive impact of pensions. We present the results in section 5 and conclude with some final reflections in section 6.
2. The Uruguayan social security system
This section describes the main characteristics and changes in the Uruguayan social security system when current retirees became eligible for retirement benefits. More specifically, we focus on the significant changes in 1979, 1995, and 2008.
In 1979, social security was organized as a public, pay-as-you-go, defined benefits system, which included minimum and maximum pensions as a redistributive element. The minimum age to qualify for a contributory pension was 60 for men and 55 for women, and both had to contribute for at least 30 years to be eligible. Also, retirement could be granted with 10 years of contribution at the ages of 70 and 65 for men and women, respectively. The salaries considered for determining the basic retirement salary were not fully representative of individuals’ contribution history, as only the last three years were considered. This could create perverse incentives, such as agreements between employers and employees to increase declared salaries towards the end of their work. Additionally, the technical replacement rate applied to pension benefits varied with age and years of accumulated service, but only in increments of five years, which provided little incentive for delaying retirement within each age/vesting period bracket.
In 1996, the social security system was reformed with the primary goal of improving fiscal sustainability. The key objective was to postpone retirement by extending the minimum years of contribution necessary to qualify for benefits, increasing the minimum retirement age for women, and improving actuarial equity. The minimum years of contribution required for standard retirement were immediately raised to 35, while the minimum retirement age for women gradually increased, reaching 60. As for deferred retirement, the minimum required years of service were gradually elevated from 10 to 15, and the minimum retirement age for women was progressively raised from 65 to 70.
Additionally, systematic registration of employment histories was implemented, accompanied by an extension of the timeframe used to calculate the basic retirement salary for both types of benefits. The calculation now considers the average monthly salaries from the last ten years of registered service in the employment history or the best twenty years if it results in a more favorable outcome for the worker. Furthermore, minimum and maximum retirement benefits were upheld with certain modifications.
Starting April 1, 1996, the Uruguayan pension system became a mixed system for individuals under 40 and those entering the labor market after that date. A transitional regime covered those aged 40 or older and was only subject to the parametric changes described in the preceding paragraphs. The mixed system comprises two complementary pillars: intergenerational solidarity and individual savings accounts. The intergenerational solidarity pillar operates on a pay-as-you-go basis, is publicly administered, and provides defined benefits. On the other hand, the individual savings pillar operates on a funded basis, can be publicly or privately administered, and involves defined contributions. The intergenerational solidarity pillar exclusively covers individuals with lower incomes unless they explicitly choose otherwise. Both pillars cover all other individuals.
There is an income cap beyond which contributions are voluntary, indirectly capping the benefits of the pay-as-you-go pillar. The minimum retirement benefit, which includes both pillars, increased as of July 2019 to 3 Base de prestaciones y contribuciones (approximately U$13 557 as of January 2020, roughly USD$340).
The system is financed through personal contributions (15% of earnings), employer contributions (7.5% percent of earnings), specific taxes, and general revenues. The pay-as-you-go pillar is funded by a portion of personal contributions and the entirety of employer contributions, and due to its deficit, it also receives funding from general revenues and taxes. The funded pillar is financed by a portion of personal contributions accumulated in the individual account along with generated returns. Upon retirement, the worker starts receiving a pension from the pay-as-you-go pillar and a monthly income based on the accumulated amount in their account, gender, and age if they contribute to the funded pillar. This pillar includes collective capitalization insurance, providing coverage for disability and death risks during employment. Starting in 2001, contributors to both pillars can choose to cease contributions to the individual account pillar at 65 and receive a life annuity based on their accumulated funds, regardless of the number of contribution years or their status in the pay-as-you-go pillar.
The Constitution establishes that pension adjustment for both pillars cannot be lower than the evolution of the Average Nominal Wage Index.
Since the 2008 reform, individuals have been eligible for ordinary pensions at 60, having accumulated at least 30 years of contributions. In this scenario, the replacement rate is 45% of the basic retirement salary. It gradually increases by 1 percentage point (pp) for each contribution year exceeding 30, up to a maximum of 35 years of contribution. Additionally, for each year of contribution exceeding 35, 0.5 pp are added with a maximum of 2.5. Also, each year, the retirement age is delayed beyond 60, and after completing 35 years of service, an extra 3 pp are added, up to a maximum of 30%. However, if at 60, the worker has yet to complete 35 years of service, 2 pp are added for each year exceeding 60 until reaching 70 or completing 35 years of contributions.
At 65, individuals can qualify for retirement if they have accumulated 25 years of contributions. This requirement decreases by two years for each additional year of age. The replacement rate is 50% of the basic retirement salary, with an additional 1 pp for each year of contributions exceeding the respective minimum years of service, up to a maximum of 14 pp.
In all cases, women receive an additional year of service for giving birth a child or adopt a minor or disabled child, up to a maximum of five years. This benefit applies to women fulfilling retirement requirements and improving the replacement rate in the pay-as-you-go pillar.
This brief description of the regulations in effect in the Uruguayan social security system in recent years illustrates the importance of redistributive elements in its design. Specifically, it includes minimum pensions to ensure individuals with lower incomes receive a higher return from their contributions than those with higher incomes. Unless they explicitly choose otherwise individuals with lower incomes are exclusively covered by the public pay-as-you-go pillar, which is inherently designed to redistribute resources. This pillar ensures that retirees bear no financial risk from the pension plan.
Moreover, providing an additional year of service for each child for women operates in a redistributive manner due to the negative correlation between the number of children and income level.
It is worth emphasizing that the Uruguayan social security system operates with a deficit and relies on financial assistance from general revenues and specific taxes. This aspect is important because the level of progressivity in the taxes used to cover the deficit impacts the final distributional outcome.
Financial assistance declined in the 2000s until 2011, after which it rose again (Brovia, 2010; Ministerio de Economía y Finanzas [MEF], 2018). Over the past decade, financial assistance has increased to slightly over 1% of GDP. Furthermore, taxes have gained prominence over time, growing from just over 3% of GDP to nearly 4% and surging from slightly over 20% of the Banco de Previsión Social (BPS) revenues to 35% (BPS, 2024). The easing of access conditions established in 2008 played a pivotal role in driving this upturn (Lavalleja and Tenenbaum, 2017).
The contribution derived from general revenues includes the collection of various types of taxes and income generated by public enterprises. Taxes are composed of 7 pp of vat, the Social Security Financing Contribution Tax (COFIS) until June 2007, the Social Security Assistance Tax (IASS) starting from July 2008, and the Special Contribution from General Revenues created by Law 18 083 since 2007. The allocation of taxes to each type of benefit is not predetermined, except for the IASS, where the total collected is assigned to the Old-Age, Survivors and Disability Insurance (OASDI) program (Brovia, 2010).
In 2018, the transfers from the Ministry of Economy and Finance to the BPS for social security assistance amounted to U$69 524 million (about USD$1 738 million) from revenue and U$21 070 million in financial assistance (about USD$527 million). The revenue comprised 70% VAT, 15% IASS, and 15% Law 18 083. It is important to note that VAT is a highly regressive tax that represents a significant portion of the additional financing obtained by the BPS.
3. Alternatives for measuring the distributional impact of pensions
In this section, we will delve into various methodological aspects that must be considered when studying the distributive impact of pensions.
A retirement system can be considered progressive if, in relative terms, the benefit received from the social security system decreases as income levels increase. In contributory programs, individuals with higher incomes often receive higher gross benefits because the benefit is tied to their formal wages in the labor market. However, by solely looking at gross benefits, the program’s distributive impact is not evident.
While it is common to find analyses that use gross benefits, it is more accurate to consider the benefits net of the contributions paid to finance them throughout one’s life. This flow corresponds to the discounted sum of all the benefits a person receives until death minus the present value of all the contributions made. Regarding contributions, there are direct and indirect ones. Direct contributions should consider personal contributions to social security and employer contributions (Hamermesh and Rees, 1993; Gruber, 1999; Brown et al., 2009). However, it is true that employer contributions to social security result in lower wages for the worker; it is arguable that it is a one-to-one relationship. However, since there is no explicit elasticity estimation and considering that the potential bias direction is known, this is a reasonable assumption.
Regarding the indirect contributions received by the social security system, assigning payments from various types of taxes to potential beneficiaries is not straightforward. Furthermore, the progressivity of each tax type varies, adding complexity to the analysis. Forteza and Rossi (2009) demonstrate that in the Uruguayan context, conclusions about the distributive impact of social programs can significantly differ depending on whether indirect contributions are considered.
Also, studying the redistributive impact of the retirement system involves constructing a counterfactual scenario for the incomes individuals would have received had the program not existed. One possible approach is to assume that individuals would not save for retirement. However, this assumption is quite strong and artificially inflates the estimation of the program’s impact. Consequently, the reduction in poverty and inequality caused by the social security program would be overestimated due to the identification of many “false poor” in the scenario without the program (Lustig and Higgins, 2018).
These “false poor” arise from imputing near-zero retirement incomes to individuals with high labor incomes and contributions to the social security system during their active years. This assumption is not reasonable, as it is logical to assume that these individuals would save a portion of their contributions to the social security system in a private retirement plan. In this regard, Lustig and Higgins (2018) propose a scenario that considers non-contributory pension transfers and the portion of contributory pensions financed through taxes as government transfers. Although this approach provides a better approximation of the distributive impact of pensions, it cannot capture redistributions that occur among and within generations of individuals, as it allocates the deficit proportionally.
In another line of research, Forteza (2018) proposes to analyze the expected Social Security Wealth (SSW) concept. Expected SSW is the present value of the expected flow of benefits that each worker anticipates receiving, net of the contributions they expect to pay throughout their entire working life.
In broad terms, expected SSW at age e0 when the worker retires at age e, is calculated as the sum of the expected flow of discounted retirement benefits the worker would receive Be (t), minus the expected flow of discounted direct contributions to social security, C(t), and indirect contributions, I(t) if these contributions are taken into account.
Where
The results are sensitive to the chosen discount rate. The present value of retirement benefits decreases as the discount rate increases because the benefits are received after contributions. Several studies conducted for different countries have used varying discount rates. For instance, in studies conducted in the United States, Brown et al. (2009) used 2 and 4% annual discount rates, while Coile and Gruber (2001) considered a 3% annual rate. In the case of Spain, Boldrin and Jiménez-Martín (1999) chose discount rates of 3 and 1% per year. Regarding retirement incentives in the social security system of Uruguay, Álvarez et al. (2010) employed an annual discount rate of 3%, whereas Álvarez et al. (2012) used a rate of 4% per year.
For estimating the counterfactual scenario, the methodology presented by Forteza (2018) suggests comparing the wealth under the social security system with what individuals would have accumulated by saving and investing their contributions at a market interest rate.
To achieve this, we need to calculate wealth without social security, which we will denote as W. Formally, W can be calculated as follows:
Where e is the age at which the individual retires from the labor market, S represents a stipend or annuity that the individual purchases using the accumulated assets up to the retirement age. The annuity completely exhausts the voluntary savings A(t) made during their active life, compounded at the market interest rate r. The remaining variables are the same as in the calculation of the SSW. If the voluntary savings are equal to the direct contributions to the social security system, the net labor income of individuals does not differ in both cases.
It is debatable to claim that individuals would make the same savings and labor market participation decisions if the social security program did not exist or had different characteristics. Evidence suggests that people do not save enough for retirement due to issues related to incomplete information about eligibility requirements and conditions, uncertainty about factors such as years of work, life expectancy, and investment returns, behavioral factors (e.g., impatience), or insufficient income (Bosch et al., 2013). Furthermore, saving rates vary over a person’s life based on age, educational level, and socioeconomic status (Gandelman, 2015).
However, a starting point for creating a counterfactual scenario is to assume that the direct contributions to the social security system are channeled into private savings, compounded at the market interest rate, and generating income after retirement from the labor market. In this document we analyze this option as a basis for further investigation. We also perform a sensitivity analysis in which we assume that individuals save a fraction of their social security contributions: one third for those in the first income quintile, two thirds for those in the second to fourth quintiles, and the full amount for those in the richest quintile.
Finally, another element to consider is that decisions regarding participation in the formal labor market and access to contributory pensions are often made within the household rather than strictly at the individual level. However, conducting simulations that accurately represent the various family arrangements and their evolution over time becomes challenging.
The impact of the social security system, IMi, is derived from the difference between SSW and W for each individual.
In a subsequent stage, to analyze the distributive impact of the pension system, the results obtained from simulating work histories will be imputed for individuals who report being retired in the Household Survey (Instituto Nacional de Estadística [INE], 2019). To achieve this, linear regressions using Ordinary Least Squares (OLS) methodology will be estimated for different groups based on the age range of the retirees, as follows:
Where:
imi = impact of the social security system derived from the difference between SSW and W
agei = age of individual i.
sexi = a variable that takes the value 1 if the individual is female and 0 if male.
benefiti = the amount of the received benefit.
μi = the error term, which is normally distributed with mean 0 and variance σ2.
Various methodological approaches have been employed in studies concerning distributive impact in Uruguay. Forteza and Ourens (2012), through the simulation of labor histories, find that the Uruguayan system is progressive, indicating that individuals with lower incomes receive higher internal rates of return than those with higher incomes.1 In Llambí et al. (2012), the distributive impact of social public spending in Uruguay for 2009 is examined by comparing the observed income distribution with a counterfactual scenario where incomes from pensions are subtracted. The study reveals that non-contributory pensions are progressive, while contributory pensions are regressive but show slight progressivity in relative terms. Analyzing the progressivity curve, they observe that contributory pensions are relatively regressive up to the sixth decile and then become relatively progressive. Finally, Araya et al. (2017) analyze the replacement rates by income quintiles based on labor histories, finding that they are progressive, indicating a certain degree of redistribution in the system. Additionally, they find that the minimum pension in the lowest quintiles primarily causes redistribution.
4. An application to the Uruguayan case
In this section, we adopt the methodology Forteza (2018) proposed for calculating the distributive impact of pensions in Uruguay. We will use the retirees who received their benefits in 2019 as a reference, excluding the pandemic years from the analysis. Therefore, we will calculate the distributive impact for this specific population.
Based on the background and data availability, several alternatives are proposed to obtain or simulate the work income history, contributions to social security, and lifetime benefits to be received. If work histories were available, as recorded in Uruguay since 1996, they could be supplemented backward and forward, as done in Forteza et al. (2009) for 2019 retirees. However, since work history records are unavailable for this study, simulations of salary income and social security contribution trajectories for different representative individuals will be conducted. Specifically, work histories will be simulated for retirees aged between 60 and 100 in 2019.
Different scenarios are simulated based on the characteristics of the workers, such as gender, salary, years of contributions, and retirement age. The composition of the various types of workers can be analyzed by Lavalleja and Tenenbaum (2017). In the simulations, it is assumed that once formal work life begins, workers continue uninterrupted until retirement, and the years of contributions are determined by the ages at which formal work life starts and ends. There is ample evidence of low contribution density and frequent contribution interruptions in Uruguay (Lagomarsino and Lanzilotta 2004; Forteza et al., 2009; Bucheli et al., 2010; Apella et al., 2011; Lavalleja et al., 2019). Although the interruptions in formal work life are not specifically simulated, their effect is captured by simulating different durations of contribution periods. Therefore, workers with a short contribution history are assumed to have started contributing as mature adults.
It is essential to consider that representing individuals with few years of contributions as those who entered formal labor markets as mature adults may underestimate their accumulated assets, as these assets will be capitalized for a shorter period than if some of these investments had been made when they were younger adults (Rossi, 2018).
Various moments in the salary distribution of formal workers are considered, including the initial salary (which corresponds to the ages at which simulated individuals begin their formal work life) and different salary profiles. These salaries are updated using the INE Average Wage Index (AWI). In other words, the initial ages at which simulated individuals enter the labor market are selected, and different percentiles of the observed income distribution are considered at each age. This ensures the presence of individuals with different income levels in each scenario.
These simulated work histories strictly adhere to the various social security regulations that were in effect at each point in time to estimate direct contributions, replacement rates, and pension amounts (Institutional Act 9 and Transitional Regime; given the “cincuentones” law, there will be virtually no retirees under the mixed regime).
To allocate each individual’s indirect contribution to the pension program, auxiliary data sources can be used. First and foremost, it is essential to determine the percentage of the collected revenue from affected taxes that is allocated to the bps. To do this, data from the General Tax Division can be used to establish the amounts of revenue collected, and data from the BPS can be used to determine the proportion of tax payments that should be assigned to individuals as their contribution to the program, which may not remain constant over time. Finally, using the Household Expenditure and Income Survey, imputing household and individual vat payments would be possible. Undertaking such an exercise requires information regarding the social security deficit and the taxes allocated to cover it over an extensive period encompassing the active period of current retirees. Due to a lack of suitable information, indirect contributions are not considered in this document. For future studies on this subject, it would be interesting to analyze the sensitivity of the results to include indirect contributions under various assumptions.
To determine age-specific survival probabilities, we rely on mortality tables from the Central Bank of Uruguay (http://www.bcu.guy.uy), which are the same tables used in regulating the Uruguayan pension system. In these tables, the probability of death is set at one at the age of 100. While variations in mortality rates among different socioeconomic groups could impact the distributive impact of pensions, this initial analysis calculates the expected Replacement Rate (RSS) using the official mortality table updated in 2017, which applies to the contributing population under BPS.
The SSW is estimated as of January 2019, considering both direct contributions and expected benefits, using a discount rate of 3%. Consequently, SSW represents the gain or loss that a retiree expects to derive from the system as of January 2019. This outcome will be compared to the wealth in a counterfactual scenario, denoted as W, in which retirees save an amount equal to their direct contributions during their working lives and receive a lifetime income. Subsequently, regressions are estimated using Ordinary Least Squares (OLS) methodology to predict the impact based on retiree characteristics (age, gender, geographical region, benefit amount) and the outcome they receive from the retirement system. This result is then imputed for retirees in the 2019 Household Survey based on econometric regressions.
We perform a sensitivity analysis in which we assume that individuals save a fraction of their social security contributions: one third for those in the first income quintile, two thirds for those in the second to fourth quintiles, and the full amount for those in the richest quintile. Keep in mind that we focus on retirees under the general regime, who represent over 80% of Uruguay’s total retirees. We specifically exclude informal workers and low-stability formal workers (approximately 20% of the labor force are informal), banking sector employees, and many white-collar professionals with university degrees. This implies that both extremes of the income distribution in the general population are excluded from our analysis. Moreover, most stable formal workers and retirees have completed, or partially completed, secondary education. These considerations suggest that the population analyzed here is considerably more homogeneous in terms of savings than the general population.
5. Results
In order to estimate the distributive impact of pensions in Uruguay, we simulated the work histories of 1 63 5 682 retirees as of January 2019. This dataset was evenly divided between males and females, ranging in age from 60 to 100. We simulated various ages at which individuals began contributing to the social security system, ranging from 20 to 40 years old. The simulations were adjusted so that the retirement benefits of January 2019 varied between U$14 000 and U$120 000 (approximately USD$ 350 to 3 000). Additionally, it was assumed that individuals claim benefits as soon as they meet the eligibility criteria. Subsequently, the data was imputed to 366 355 retirees aged 60 and older in the 2019 Household Survey (the Appendix shows the estimations of equation 4).
The imputation results reveal that, on average, retirees experience a 6% monthly loss in the bps pension system compared to what they would receive by saving a similar amount to their direct contributions and purchasing an annuity. However, there is significant variability in the outcomes among different groups of individuals.
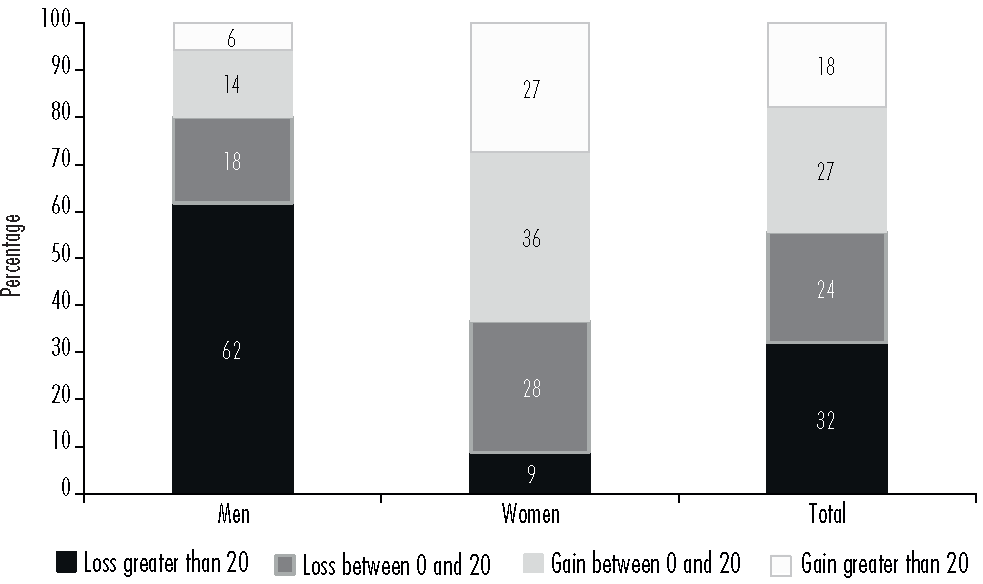
When analyzing the results based on individual characteristics such as gender, age, geographical location, and pension amount, we first observe a reaffirmation of the average overall and among different groups of individuals. Approximately one-third of retirees experience a monthly loss exceeding 20% of their pension amount, while 24% incur a loss ranging from 0 to 20%. Furthermore, 27% enjoy a gain between 0 and 20%, with only 17% experiencing a gain exceeding 20% (see Figure 1).
Source: own computations.
Figure 1 Distribution of the outcome of the BPS pension system regarding pension amount (year 2019)
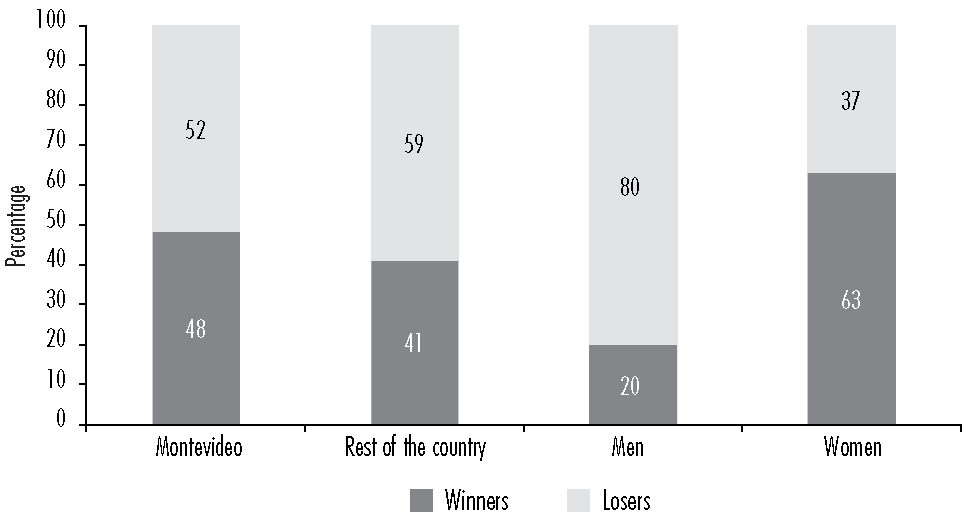
Gender differences are evident: while the system provides a pension lower than what they would have received by saving their contributions and purchasing an annuity for 80% of men, less than 40% of women experience a loss due to the existence of the pension program. Furthermore, 62% of men incur a monthly loss exceeding 20%, whereas only 9% of women experience losses of that magnitude. At the other end of the spectrum, more than a quarter of women receive monthly gains exceeding 20%, while only 6% of men find themselves in that situation. On average, women gain 6%, whereas men incur a loss of 21%. This superior outcome for women can be influenced by various factors, such as the inclusion of an additional year of contributions for each child and their longer life expectancy compared to men. Additionally, women were eligible for earlier retirement under Institutional Act 9, and only from 2003 onwards were the exact retirement requirements imposed on women as on men.
Regarding the geographical region, it’s noteworthy that 48% of retirees in Montevideo experience a gain within the BPS pension system, whereas this figure is seven pp lower in the country’s interior (see Figure 2). This difference could be attributed to lower wages in many areas of the country’s interior, although it’s worth noting that the cost of living is often lower compared to Montevideo.
Source: own computations.
Figure 2 Winners and losers in the BPS pension system by gender and region (year 2019)
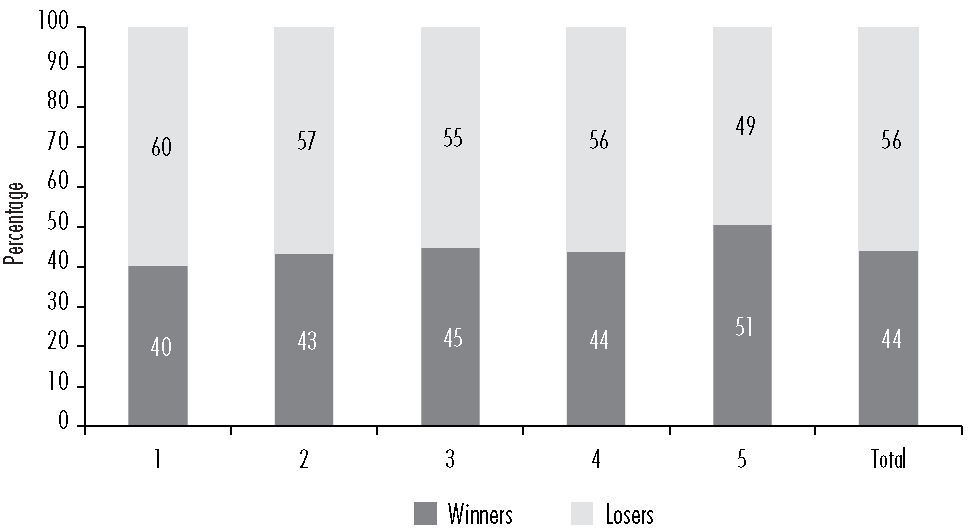
Let us look at the results by quintile distribution of benefits. Among the poorest retirees, only 40% profit from the pension system, while on average, this figure rises to 44% and more than half of the richest are winners (see Figure 3).
Source: own computations.
Figure 3 Winners and losers in the BPS pension system by quintile of benefit amount (year 2019)
This analysis of winners and losers by retirement income stratum does not clearly point to progressivity, as the share of winners is higher in the middle and upper strata than in the lower ones. However, it may be the case that poorer individuals are overrepresented among the losers, but they lose less than wealthier individuals who also lose. Moreover, women tend to gain more than men from social security, and only a small fraction of them experience significant losses. It is also important to note that, on average, women earn lower wages than men. Consistent with this interpretation, we find that pensions reduce inequality. Comparing the Gini index in the scenario with retirements to the counterfactual scenario, the former shows a less unequal distribution: in 2019, the Gini index with retirements was 0.33, while in the counterfactual scenario it reached 0.34, implying a reduction in inequality of one percentage point.
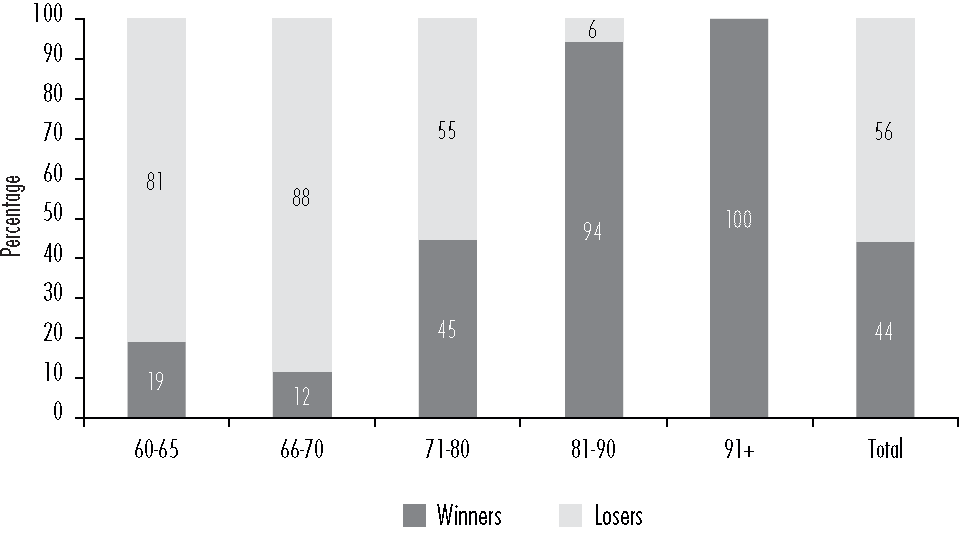
From the generational point of view, the analysis of retirees’ characteristics shows that retirees over 80 years of age obtain a markedly higher result from the retirement system compared to those received by retirees under 70 years of age (see Figure 4). This result is directly affected by the changes in the parameters of the system incorporated by the successive reforms to the pension system. In particular, the changes in the replacement rate and the years required to access the different types of benefits introduced in 1995. Practically all the retirees from Institutional Act 9 are winners. With the tightening of the conditions of access and the reductions in the generosity of the systems that usually occur over time, together with the greater possibility of control generated by the establishment of the labor history registry, there is redistribution from the younger generations to the older generations.
Source: own computations.
Figure 4 Winners and losers in the BPS pension system by age group (year 2019)
Regarding our sensitivity analysis, in a new counterfactual scenario we assume that individuals save a fraction of their social security contributions: one third for those in the first income quintile, two thirds for those in the second to fourth quintiles, and the full amount for those in the richest quintile. Under this scenario, the gains from social security by income group increase slightly. Specifically, social security winners rise by an additional 2 pp for the poorest, 5 pp for the second quintile, 2 pp for the third quintile, and 3 pp for the fourth quintile. By construction, there is no change for the richest group. The effects remain moderate because we evaluate benefits net of contributions: while social security provides higher benefits than in this counterfactual scenario, it also entails higher contributions.
6. Final reflections
Assessing the distributional impact of retirement programs is a complex analysis. If only the benefits received by individuals were considered, an incomplete analysis would be carried out since individuals contribute directly and indirectly to their financing. This paper analyzed different alternatives for estimating the distributive impact of pensions. An estimate of the impact of pensions in Uruguay was carried out using the approach of comparing the present value of expected benefits net of (direct) contributions with the hypothetical case in which there is no retirement program. The contributions are saved in an individual fund from which a life annuity is contracted at retirement.
The results indicate that the poorest retirees, men, younger individuals, and those living outside the capital are overrepresented among the losers from the existence of the retirement program. The fact that women tend to benefit from the pension system is likely related to the existence of maternity credits and their higher life expectancy compared to men, which allows them to receive benefits for a longer period. Moreover, until 2003, the eligibility conditions for women were more lenient than for men, enabling them to retire earlier and further extending their benefit-receipt period relative to men.
Conversely, retirees residing in Montevideo benefit from the retirement program to a greater extent than those living in the interior of the country. This may be explained by the higher average wages in the capital, combined with the observation that lower-income individuals are more likely to be among the losers.
Regarding generations, the fact that older retirees are almost all winners likely reflects the characteristics of the system under which they retired. The requirements for obtaining benefits under Institutional Act 9 were considerably more lenient than those introduced after 1995. Furthermore, the system provided few incentives to postpone retirement, allowing individuals to retire earlier while still extending the period during which they collected benefits. Pension amounts were also comparatively more generous.
In sum, the political economy of the pension system plays a central role in shaping these outcomes.
In terms of distributional effects, individuals with lower benefits are more likely to be among the losers, suggesting that the retirement program may not be fully progressive. Minimum pensions may not be sufficient to offset these disparities. Nevertheless, the pension system as a whole reduces inequality, as reflected in a lower Gini index when the retirement program is in place. It may be the case that low-income workers constitute a larger share of the losers, but that wealthier individuals experience greater losses.
This first analysis allows an approach to estimating the distributional impact of the pension system based on the expected wealth of social security. Different scenarios could be simulated in future studies, incorporating indirect contributions in different ways, for example. These extensions will allow us to arrive at a more robust result by analyzing the sensitivity of the result to the different parameters.

