


Serviços Personalizados
Journal
Artigo
 texto em
 Inglês (pdf)
 Artigo em XML
 Referências do artigo

 Tradução automática
 Enviar este artigo por email
Indicadores
-
 Citado por SciELO
-
 Acessos
Links relacionados
-
 Similares em
SciELO
Compartilhar

 Permalink

Contaduría y administración
versão impressa ISSN 0186-1042
Contad. Adm vol.66 no.4 Ciudad de México Out./Dez. 2021 Epub 02-Set-2024
https://doi.org/10.22201/fca.24488410e.2022.2891
Articles
Determinants of the probability of access to insurance in Colombia
1Instituto Tecnológico Metropolitano, Colombia
This study offers empirical evidence about the deciding factors of the insurance access in Colombia, which is actually included on the national financial inclusion policies recommended by AFI, using as a primary input the Inclusion Insurance Survey made by the government through Banca de las Oportunidades, Superintendencia Financiera and Fasecolda. Among the main results reached are: the mandatory insurance access probability, credit induced or not, is more significant for men. It is increased according to household size, economic status, and age, but not in a linear function. It also increases when people are both working and studying or are only studying, as well as when they have savings, credit, their own house, business or company, or technical, technological, or postgraduate studies.
Keywords: Financial exclusion; Financial inclusion; Insurance; Probabilistic models
JEL Code: D14; G22; G50
El presente estudio ofrece evidencia empírica sobre los determinantes del acceso a los seguros en Colombia, los cuales han sido incluidos recientemente dentro de las políticas nacionales de inclusión financiera, recomendadas por la AFI, utilizando como insumo principal la Encuesta de Inclusión en Seguros realizada por el gobierno a través de la Banca de las Oportunidades, la Superintendencia Financiera y Fasecolda. Dentro de los principales resultados se encuentra que la probabilidad de acceder a un seguro obligatorio ya sea inducido por la adquisición de un crédito o no, es mayor para los hombres y aumenta con el tamaño del hogar, el estrato socioeconómico y la edad, aunque de forma no lineal. Específicamente se incrementa para aquellas personas que se encuentran trabajando y estudiando simultáneamente o sólo estudiando y para aquellas personas que cuentan con una vivienda propia, un negocio o empresa, que tienen ahorros, créditos y que tienen un nivel educativo técnico, tecnológico o de posgrado.
Palabras clave: Exclusión financiera; Inclusión financiera; Seguros; Modelos de probabilidad
Código JEL: D14; G22; G50
Introduction
Financial exclusion is when many potential consumers do not have access to and do not use financial services appropriately (Devlin, 2005)1. Many emerging and developed countries have included strategies to advance financial inclusion in their policy agendas to achieve essential objectives such as equity and poverty reduction and promote financial stability, employment, and economic growth. Colombia, for example, adopted a financial inclusion policy in 2006, which led to the creation of the "Banca de las Oportunidades" Investment Program (Decree 3078 of 2006) to facilitate access to financial services for the lower-income population, implementing various strategies such as expansion of regional geographic coverage, creation of simplified savings products with lower costs and access requirements, promotion of credit granting with maximum interest rate differentiation for microcredits, and the development of inclusive insurance through marketing in networks and non-bank correspondents.
The focus on insurance demand in this study is for two main reasons. First, to use the information contained in the first insurance inclusion survey conducted in the country, which represents the first national effort to understand the behavior of Colombians regarding access to and use of insurance in the economy and the different protection and assurance systems used. Second, to fill the gap in the literature regarding the analysis of the determinants of insurance demand that help consumers protect themselves against adverse events. Instead, studies have focused on investigating the determinants of access to financial products such as credit, savings accounts, and debit and credit cards. Thus, this study aims to provide empirical evidence on the determinants of financial exclusion regarding access to insurance, estimating different econometric models, including the linear probability model (LPM), logit, and probit. In general, the results show that the probability of having access to mandatory insurance, whether induced by the acquisition of a loan or not, is higher for men and increases with household size, socioeconomic stratum, and age. Nonetheless, in a non-linear way, it increases for those working and studying simultaneously or only studying and those with their own home, a business, or a company, who have savings, loans, and a technical, technological, or postgraduate level of education.
This article is divided into five sections, including the introduction. The review of the literature describes national and international studies that analyze the determinants of access to financial services. The methodology section details the survey used, the relevant data for this study, and the econometric model. The last two sections present the research results and conclusions.
Financial exclusion is when many potential consumers do not have access to and do not use financial services appropriately (Devlin, 2005)2. Many emerging and developed countries have included strategies to advance financial inclusion in their policy agendas to achieve essential objectives such as equity and poverty reduction and promote financial stability, employment, and economic growth. Colombia, for example, adopted a financial inclusion policy in 2006, which led to the creation of the "Banca de las Oportunidades" Investment Program (Decree 3078 of 2006) to facilitate access to financial services for the lower-income population, implementing various strategies such as expansion of regional geographic coverage, creation of simplified savings products with lower costs and access requirements, promotion of credit granting with maximum interest rate differentiation for microcredits, and the development of inclusive insurance through marketing in networks and non-bank correspondents.
The focus on insurance demand in this study is for two main reasons. First, to use the information contained in the first insurance inclusion survey conducted in the country, which represents the first national effort to understand the behavior of Colombians regarding access to and use of insurance in the economy and the different protection and assurance systems used. Second, to fill the gap in the literature regarding the analysis of the determinants of insurance demand that help consumers protect themselves against adverse events. Instead, studies have focused on investigating the determinants of access to financial products such as credit, savings accounts, and debit and credit cards. Thus, this study aims to provide empirical evidence on the determinants of financial exclusion regarding access to insurance, estimating different econometric models, including the linear probability model (LPM), logit, and probit. In general, the results show that the probability of having access to mandatory insurance, whether induced by the acquisition of a loan or not, is higher for men and increases with household size, socioeconomic stratum, and age. Nonetheless, in a non-linear way, it increases for those working and studying simultaneously or only studying and those with their own home, a business, or a company, who have savings, loans, and a technical, technological, or postgraduate level of education.
This article is divided into five sections, including the introduction. The review of the literature describes national and international studies that analyze the determinants of access to financial services. The methodology section details the survey used, the relevant data for this study, and the econometric model. The last two sections present the research results and conclusions.
Review of the literature
The role of financial inclusion in economic growth, financial stability, and inequality has been extensively studied in the literature (Fowowe, 2020; Wokabi & Fatoki, 2019; Ahamed & Mallick, 2019; Dunham, 2019; Mehrotra & Yetman, 2015; Simpson & Buckland, 2009), as well as the macroeconomic and microeconomic factors that influence the levels of financial inclusion in a country. Such has been its importance that the Agency for Financial Inclusion (AFI), since its creation in 2008, has promoted global strategies and recommendations on sustainable and inclusive policies to increase the accessibility of financial services for the population excluded from the system, due to its potential to improve the welfare of individuals and households, boost new entrepreneurs, increase employment, and foster the efficiency of certain social and economic policies.
Generally, the determinants of financial exclusion or factors affecting the holding of financial products have been classified into two groups: demand factors and supply factors. Within the first group are variables such as gender, age, household size, income, type of work, region, race, social stratum, educational level, receipt of subsidies, and type of housing. Factors such as cost, availability of access points, infrastructure, requirements for acquiring a financial product, and technology are identified as supply factors. Most studies have concentrated on the impact of demand factors on financial inclusion within the literature analyzed.
Several authors have analyzed the determinants of financial inclusion in the international context. For example, at the macroeconomic level, Raichoudhury (2020), after constructing a financial inclusion index for each of the states in India, finds that the main factors affecting financial inclusion are income, infrastructure (measured through the length of roads and the presence of companies), and employment opportunities. Similarly, Boitano and Abanto (2020) investigate the determinants of financial inclusion in Peru at the departmental level. The authors find that bank concentration, as measured by the Herfindahl-Hirschman Index (HHI), negatively affects inclusion levels, while technology affects it positively, but its effect has been fading over time. Taking into account a microeconomic approach to the individual characteristics that affect financial inclusion, Martinez et al. (2020) study the determinants of financial inclusion in seven Latin American countries using probabilistic models. Inclusion is measured as access to one of the following financial instruments: bank account, savings, and credit. Its main results are that older, in wealthier quintiles, and more educated males are more likely to use any financial instrument.
Meanwhile, Sanderson, Learnmore, and Pierre Le (2018) do so for the case of Zimbabwe, where they find that age, education, financial literacy, income, and internet connection positively affect inclusion. Nevertheless, in line with Iregui-Bohórquez et al. (2016) and Martinez et al. (2020), the relation with age is positive and decreasing, i.e., at retirement age, interest in financial services is lost. In addition, supply factors such as the documentation required to open a savings account and the distance to access points negatively affect inclusion. To overcome this last barrier, the Central Bank of Zimbabwe has enabled the acquisition of bank accounts for low-income earners by minimizing the documentation required, which can somewhat compromise the financial system's stability. Likewise, Wokabi and Fatoki (2019) identify that factors such as the proportion of people living in rural areas and low-income levels are negatively related to financial inclusion in East African countries. In the case of Tuesta et al. (2014), they found that the main factors of financial inclusion in Mexico, measured through an aggregate indicator that considers access to credit and savings, are age, position in the household, marital status, and education. In turn, Tuesta et al. (2015) study the determinants of financial exclusion in Argentina and use probit models to identify the variables that influence the probability of being excluded from the formal financial sector, measured through having or not having a bank account. Among their main results, they found that there is a positive relation between the use of financial products and education, income, and age. Simpson and Buckland (2009) define financial exclusion as not having access to any formal financial product, whether payment, savings, or credit, and estimate probit models to determine the factors that influence it. They suggest a non-linear relation between financial exclusion and income and wealth variables. That is, if income or wealth falls, financial exclusion increases at an increasing rate. They also find important regional differences and that education, household structure, home ownership, and financial education impact financial exclusion.
Salignac, Marjolin, Reeve, and Muir (2019) define the concept of financial resilience for the Australian case. The authors indicate that financial resilience refers to an individual's ability to access and leverage external capabilities and resources in times of financial adversity. This approach could be categorized among those of the demand perspective, but it goes beyond the description of population characteristics since it intrinsically analyzes the individual to determine their capacity to access financial resources.
For the Colombian case, most of the studies analyze the determinants of access to different kinds of credit (Rodríguez & Riaño, 2016; Pacheco & Yaruro, 2016; Gómez et al., 2016; Cano et al., 2013; Murcia-Pabón, 2007). Others emphasize the differences between rural and urban areas (Estrada & Zamora, 2017) or between the formal and informal sectors (Iregui-Bohórquez et al., 2016). Specifically, Murcia-Pabón (2007) studies the determinants of access to housing credit and credit cards and, using the information contained in the 2003 Quality of Life Survey, finds that the socio-demographic characteristics of households such as education, income level, wealth, labor contract ownership, age and geographic position are determinants of access to credit by Colombian households.
Another outstanding study is that of Anaya, Buelvas, and Romero (2020), who study the importance of monetary poverty in financial inclusion in the department of Córdoba. The authors establish that factors such as the educational level of the head of the household and living in an urban area increase the probability of accessing financial services.
Estrada and Zamora (2017) analyze financial inclusion in terms of credit in Colombia's rural sector. Their results show that the persistence of these gaps is related to supply-side problems, i.e., high concentration of financial infrastructure in the cities, the existence of products that are inadequate for the needs of the rural population, information imbalances, and lack of competition in the financial market. On the other hand, Iregui-Bohórquez et al. (2016) find that the probability of obtaining credit is positively related to the following variables: education, income, household size, home ownership, labor force participation, and marital status. In the case of formal credit, they find that income and education affect it positively. In contrast to the studies mentioned above, the authors find no significant differences between rural and urban areas, and gender is not a significant variable.
Gómez et al. (2016) include other factors, such as trust in the financial system and Sisben membership, as possible determinants of the demand for non-cash payment mechanisms, such as savings accounts and credit cards. The results show that geographic location, Sisben membership, insurance coverage, education, employment formality, income, and trust in the financial system are significant for holding this type of account. In the case of credit cards, they find that employment status and age also explain their demand.
Pacheco and Yaruro (2016) use the contingency table methodology to study the factors that affect a person's decision not to acquire financial products, despite knowing their existence. Among their main results, they found that a low level of income and education, the lack of a budget, vulnerability in the labor market, and not having direct responsibility for money management in the household explain to a large extent the lack of financial products, despite being aware of them. An interesting finding is that gender and age are unrelated to not holding financial products, despite knowing about them.
The following describes the few studies that have focused on analyzing the variables that influence the demand for insurance. Devlin (2005) studies the probability of being excluded from a range of financial products, namely checking, savings, life insurance, or pension accounts, and estimates a logit model for each product. Unlike Cano et al. (2013), Devlin analyzes access to financial products separately and estimates a logit model for each. He finds that type of employment, household income, home ownership, marital status, age, and education are important in explaining exclusion.
Meanwhile, Rodríguez and Riaño (2016) estimate a probit and logit model to determine the probability of having a financial product such as savings, credit, and insurance, and an additional variable constructed as the holding of any financial products, to measure financial inclusion. Their main results suggest that household wealth, educational level, and job stability increase the probability of acquiring a financial product. On analyzing the particular case of insurance, they find that the probability of access is related to household income, home ownership and risk, and the propensity of the home to suffer risks such as floods, avalanches, flooding, landslides, subsidence, or earthquakes.
In the study by Cano et al. (2013), an index of access to the financial system is constructed, where 13 financial products, formal and informal, are included to avoid wasting the information in the survey. Although the authors do not analyze the insurance variable independently, it was included in the construction of the indicator, which suggests its importance as a vehicle for an individual's financial inclusion. The main results show that gender, age, marital status, number of family members, income, wealth, level of schooling, and financial education are significant variables in access to financial services.
Finally, the study by Dorn et al. (2017), which focuses on the field of health insurance, finds that increases in the age of individuals are related to a lower probability of purchasing insurance if previously uninsured, while an increase in the value of assets increases this probability. For individuals who had insurance but declined it later, increases in age also reduce their probability of acquiring it, just as the perceived probability of accessing a nursing home reduces this probability. Likewise, an increase in the number of children, a reduction in the value of assets, and a deterioration in the spouse's health are factors that increase the likelihood of purchasing long-term insurance if one did not have it before.
The role of financial inclusion in economic growth, financial stability, and inequality has been extensively studied in the literature (Fowowe, 2020; Wokabi & Fatoki, 2019; Ahamed & Mallick, 2019; Dunham, 2019; Mehrotra & Yetman, 2015; Simpson & Buckland, 2009), as well as the macroeconomic and microeconomic factors that influence the levels of financial inclusion in a country. Such has been its importance that the Agency for Financial Inclusion (AFI), since its creation in 2008, has promoted global strategies and recommendations on sustainable and inclusive policies to increase the accessibility of financial services for the population excluded from the system, due to its potential to improve the welfare of individuals and households, boost new entrepreneurs, increase employment, and foster the efficiency of certain social and economic policies.
Generally, the determinants of financial exclusion or factors affecting the holding of financial products have been classified into two groups: demand factors and supply factors. Within the first group are variables such as gender, age, household size, income, type of work, region, race, social stratum, educational level, receipt of subsidies, and type of housing. Factors such as cost, availability of access points, infrastructure, requirements for acquiring a financial product, and technology are identified as supply factors. Most studies have concentrated on the impact of demand factors on financial inclusion within the literature analyzed.
Several authors have analyzed the determinants of financial inclusion in the international context. For example, at the macroeconomic level, Raichoudhury (2020), after constructing a financial inclusion index for each of the states in India, finds that the main factors affecting financial inclusion are income, infrastructure (measured through the length of roads and the presence of companies), and employment opportunities. Similarly, Boitano and Abanto (2020) investigate the determinants of financial inclusion in Peru at the departmental level. The authors find that bank concentration, as measured by the Herfindahl-Hirschman Index (HHI), negatively affects inclusion levels, while technology affects it positively, but its effect has been fading over time. Taking into account a microeconomic approach to the individual characteristics that affect financial inclusion, Martinez et al. (2020) study the determinants of financial inclusion in seven Latin American countries using probabilistic models. Inclusion is measured as access to one of the following financial instruments: bank account, savings, and credit. Its main results are that older, in wealthier quintiles, and more educated males are more likely to use any financial instrument.
Meanwhile, Sanderson, Learnmore, and Pierre Le (2018) do so for the case of Zimbabwe, where they find that age, education, financial literacy, income, and internet connection positively affect inclusion. Nevertheless, in line with Iregui-Bohórquez et al. (2016) and Martinez et al. (2020), the relation with age is positive and decreasing, i.e., at retirement age, interest in financial services is lost. In addition, supply factors such as the documentation required to open a savings account and the distance to access points negatively affect inclusion. To overcome this last barrier, the Central Bank of Zimbabwe has enabled the acquisition of bank accounts for low-income earners by minimizing the documentation required, which can somewhat compromise the financial system's stability. Likewise, Wokabi and Fatoki (2019) identify that factors such as the proportion of people living in rural areas and low-income levels are negatively related to financial inclusion in East African countries. In the case of Tuesta et al. (2014), they found that the main factors of financial inclusion in Mexico, measured through an aggregate indicator that considers access to credit and savings, are age, position in the household, marital status, and education. In turn, Tuesta et al. (2015) study the determinants of financial exclusion in Argentina and use probit models to identify the variables that influence the probability of being excluded from the formal financial sector, measured through having or not having a bank account. Among their main results, they found that there is a positive relation between the use of financial products and education, income, and age. Simpson and Buckland (2009) define financial exclusion as not having access to any formal financial product, whether payment, savings, or credit, and estimate probit models to determine the factors that influence it. They suggest a non-linear relation between financial exclusion and income and wealth variables. That is, if income or wealth falls, financial exclusion increases at an increasing rate. They also find important regional differences and that education, household structure, home ownership, and financial education impact financial exclusion.
Salignac, Marjolin, Reeve, and Muir (2019) define the concept of financial resilience for the Australian case. The authors indicate that financial resilience refers to an individual's ability to access and leverage external capabilities and resources in times of financial adversity. This approach could be categorized among those of the demand perspective, but it goes beyond the description of population characteristics since it intrinsically analyzes the individual to determine their capacity to access financial resources.
For the Colombian case, most of the studies analyze the determinants of access to different kinds of credit (Rodríguez & Riaño, 2016; Pacheco & Yaruro, 2016; Gómez et al., 2016; Cano et al., 2013; Murcia-Pabón, 2007). Others emphasize the differences between rural and urban areas (Estrada & Zamora, 2017) or between the formal and informal sectors (Iregui-Bohórquez et al., 2016). Specifically, Murcia-Pabón (2007) studies the determinants of access to housing credit and credit cards and, using the information contained in the 2003 Quality of Life Survey, finds that the socio-demographic characteristics of households such as education, income level, wealth, labor contract ownership, age and geographic position are determinants of access to credit by Colombian households.
Another outstanding study is that of Anaya, Buelvas, and Romero (2020), who study the importance of monetary poverty in financial inclusion in the department of Córdoba. The authors establish that factors such as the educational level of the head of the household and living in an urban area increase the probability of accessing financial services.
Estrada and Zamora (2017) analyze financial inclusion in terms of credit in Colombia's rural sector. Their results show that the persistence of these gaps is related to supply-side problems, i.e., high concentration of financial infrastructure in the cities, the existence of products that are inadequate for the needs of the rural population, information imbalances, and lack of competition in the financial market. On the other hand, Iregui-Bohórquez et al. (2016) find that the probability of obtaining credit is positively related to the following variables: education, income, household size, home ownership, labor force participation, and marital status. In the case of formal credit, they find that income and education affect it positively. In contrast to the studies mentioned above, the authors find no significant differences between rural and urban areas, and gender is not a significant variable.
Gómez et al. (2016) include other factors, such as trust in the financial system and Sisben membership, as possible determinants of the demand for non-cash payment mechanisms, such as savings accounts and credit cards. The results show that geographic location, Sisben membership, insurance coverage, education, employment formality, income, and trust in the financial system are significant for holding this type of account. In the case of credit cards, they find that employment status and age also explain their demand.
Pacheco and Yaruro (2016) use the contingency table methodology to study the factors that affect a person's decision not to acquire financial products, despite knowing their existence. Among their main results, they found that a low level of income and education, the lack of a budget, vulnerability in the labor market, and not having direct responsibility for money management in the household explain to a large extent the lack of financial products, despite being aware of them. An interesting finding is that gender and age are unrelated to not holding financial products, despite knowing about them.
The following describes the few studies that have focused on analyzing the variables that influence the demand for insurance. Devlin (2005) studies the probability of being excluded from a range of financial products, namely checking, savings, life insurance, or pension accounts, and estimates a logit model for each product. Unlike Cano et al. (2013), Devlin analyzes access to financial products separately and estimates a logit model for each. He finds that type of employment, household income, home ownership, marital status, age, and education are important in explaining exclusion.
Meanwhile, Rodríguez and Riaño (2016) estimate a probit and logit model to determine the probability of having a financial product such as savings, credit, and insurance, and an additional variable constructed as the holding of any financial products, to measure financial inclusion. Their main results suggest that household wealth, educational level, and job stability increase the probability of acquiring a financial product. On analyzing the particular case of insurance, they find that the probability of access is related to household income, home ownership and risk, and the propensity of the home to suffer risks such as floods, avalanches, flooding, landslides, subsidence, or earthquakes.
In the study by Cano et al. (2013), an index of access to the financial system is constructed, where 13 financial products, formal and informal, are included to avoid wasting the information in the survey. Although the authors do not analyze the insurance variable independently, it was included in the construction of the indicator, which suggests its importance as a vehicle for an individual's financial inclusion. The main results show that gender, age, marital status, number of family members, income, wealth, level of schooling, and financial education are significant variables in access to financial services.
Finally, the study by Dorn et al. (2017), which focuses on the field of health insurance, finds that increases in the age of individuals are related to a lower probability of purchasing insurance if previously uninsured, while an increase in the value of assets increases this probability. For individuals who had insurance but declined it later, increases in age also reduce their probability of acquiring it, just as the perceived probability of accessing a nursing home reduces this probability. Likewise, an increase in the number of children, a reduction in the value of assets, and a deterioration in the spouse's health are factors that increase the likelihood of purchasing long-term insurance if one did not have it before.
Methodology
Some studies have analyzed the determinants of financial exclusion from an econometric perspective (Zins & Weill, 2016; Altunbaş, Thornton, & Kara, 2010; Rodríguez & Riaño, 2016; Devlin, 2005). The main factors include income level, region of residence, gender, educational level, and age. This study applies LPM, logit, and probit models to identify the determinants of financial exclusion in Colombia measured through a discrete variable that takes two values, one if the individual has compulsory or induced insurance and zero otherwise. The compulsory or induced insurances considered are life, school accidents, fire or earthquake (home or business), automobile, SOAT (compulsory traffic accident insurance), and unemployment. For induced insurance, it was considered whether the acquisition of the insurance was linked to the acquisition of a loan, that is, whether the insurance acquired was tied to a requested loan, while for compulsory insurance, only whether or not the person had this type of insurance. Therefore, the dependent variable accounts for whether the individual has induced insurance, compulsory insurance, or both, in which case it has a value of 1. Otherwise, the variable takes the value of zero.
The database used corresponds to the "first study of insurance demand in Colombia" survey carried out by the Financial Superintendence of Colombia, Banca de las Oportunidades, and Fasecolda3. The database has a total of 6 520 households surveyed in 89 municipalities and 23 departments of Colombia, with a national statistical representation at a maximum margin of error of 4.5% and a confidence level of 95% (Banca de las Oportunidades, Superfinanciera, et al., 2018).
An LPM, logit, or probit regression model is an econometric representation in which a dependent variable (or response variable), which must be discrete (usually dichotomous), is related to one or more independent variables, which can be continuous or discrete. The functional form taken by each of these models is described below,
Where
The set of independent variables Xji comprises a series of characteristics associated with each individual within the sample. Devlin (2005) points out that factors such as gender, social class, age, marital status, and household income, among others, are good predictors of the probability of acquiring a financial service or insurance. For Colombia, Rodríguez and Riaño (2016) find that the main credit access determinants are income level, education, and job stability. Meanwhile, Cano et al. (2013), to fit linear regression models that enable them to explain a set of indicators of access to the financial system, use an index of economic variables, a liquidity index, an index of intertemporal preferences, an index of financial attitudes, and an index of financial knowledge. In addition, the authors control for socio-demographic variables such as age, gender, marital status, household size, level of schooling, number of financial establishments, and participation in government programs.
Table 1 describes the independent variables to be considered in this study.
Table 1 Description of the independent variables of the model
| Variable name | Description | Unit of measurement | Expected sign |
| Number of people in the household | Number of people living in the household | Number of people | Positive |
| Gender | Person's gender | Dummy variable, 1: man, 0: woman | Negative |
| Age | Age of respondent | Years | Positive for age and negative for age squared |
| Type of residence | Type of dwelling in which the person lives | Dummy variable. 1: House, 0: Apartment or other | Positive |
| Stratum | Socioeconomic stratum of the dwelling | Dummy variable. A dummy variable is defined for each stratum from 1 to 6, where 7 indicates no stratum. | Positive/Negative |
| Type of dwelling | Description of home ownership or not | Dummy variable. 1: owned (wholly or partially), 0: leased | Positive |
| Owns a company, establishment or business | Description of ownership or non-ownership of a place of business or establishment | Dummy variable. 1: Yes, 0: No | Positive |
| Savings holdings | Description of whether or not savings are held | Dummy variable. 1: Yes, 0: No | Positive |
| Credit holding | Description of whether or not credits are held | Dummy variable. 1: Yes, 0: No | Positive |
| Educational level | Educational level of the person | Dummy variable. A dummy variable is defined for each educational level, from preschool to postgraduate level | Positive/Negative |
| Economic activity | Main economic activity of the person | Dummy variable. A dummy variable is defined for each economic activity: 1. Working, 2. Working and studying, 3. Retired, 4. Looking for a job, 5. Studying, 6. Household trades, 7. Permanently disabled for work, 8. Other activity. | Positive/Negative |
| Last month's income | Respondent's monthly income | Dummy variable. Dummy variables are defined from COP 500 000 to COP 4 000 000 or more, and a category for do not know / no answer. | Positive |
| Rurality | Area of residence | Dummy variable. 1. Cities and urban areas. 0. Intermediate, rural, or dispersed rural municipalities. | Positive |
Source: created by the authors, 2019
Financial inclusion in Colombia
In recognition of the changes generated by the government to promote financial inclusion, the Global Microscope 2018 ranked Colombia as the country with the best regulatory and institutional environment for financial inclusion within a sample of 55 countries (The Economist, 2018). Nevertheless, financial inclusion data show the low ownership of financial products by Colombian households and a low level of knowledge about the characteristics of these products.
Colombia, through the Banca de las Oportunidades, Fasecolda, and the Superintendencia Financiera, has developed several surveys on demand for financial products, intending to diagnose the state of financial inclusion in the country and provide a complete picture of the progress, challenges, and opportunities for strengthening the sector. In addition, it seeks to provide information to the government and financial institutions for the design of public policies and the supply of financial services tailored to the characteristics and needs of the demand. The surveys inquire about financial inclusion indicators in terms of access, use, quality, and well-being, which is equivalent to a broader concept of inclusion, detached from the mere fact of accessing a financial product.
The first financial inclusion survey results suggest that supply-side constraints to financial sector access are virtually non-existent. 96% of microentrepreneurs and 95% of individuals report having access to at least one point of service that works for them. Nevertheless, only 55% of microentrepreneurs and 67% of individuals report having at least one financial product. The main barriers to access are related to self-exclusion and insufficient income. Regarding insurance demand, 28% of microentrepreneurs and 50% of individuals have compulsory or voluntary insurance, and people's insurance holdings are due to some form of funeral protection. Among the main barriers to access to insurance for microentrepreneurs and individuals are self-exclusion, insufficient income, and lack of financial education. In the case of individuals, women and people of lower socioeconomic status report lower insurance holdings. In the second sample of this survey, there was an increase in the ownership of at least one financial product by individuals (77%), but no change was reported for microentrepreneurs. Self-exclusion continues to be an essential factor in why Colombians do not use transactional or credit products, i.e., they consider that they do not need them (Superintendencia Financiera & Banca de las Oportunidades, 2017).
The third financial inclusion survey conducted in Colombia, but focused on insurance, demonstrates the government's interest in strengthening its national financial inclusion strategies (NFIS). Table 2 shows that only 15% of respondents have ever had insurance, only 18% have had life insurance, 2% have purchased unemployment insurance, and less than 1% have had agricultural insurance. However, the figure is considerably higher regarding having EPS-POS insurance (76%) and funeral insurance (53.4%).
Table 2 Access to insurance in Colombia (%)
| Type of insurance | Yes | No |
| Life | 17.7 | 82.3 |
| Funeral | 53.48 | 46.52 |
| Personal accidents | 13.51 | 86.49 |
| School accidents | 3.85 | 96.15 |
| EPS-POS | 76.23 | 23.77 |
| Educational | 2.27 | 97.73 |
| Fire/earthquake Household | 2.5 | 97.5 |
| Fire/earthquake Business | 0.48 | 99.52 |
| Unemployment | 2.27 | 97.73 |
| ARL | 23.91 | 76.09 |
| Agricultural | 30.51 | 69.49 |
| SOAT | 30.51 | 69.49 |
| Vehicle | 1.21 | 98.79 |
| Civil liability | 1.21 | 98.79 |
Source: Insurance demand survey 2018
Specifically, this insurance survey shows that the penetration of these types of insurance is low and equal to 27%, representing a great opportunity for the sector to expand. The main barrier to not acquiring insurance is its cost, and the main reasons for acquiring it are related to the protection of household members and being able to have peace of mind in the face of future uncertainties (Banca de las Oportunidades, Superintendencia Financiera, et al., 2018).
Table 3 shows some key indicators of financial inclusion in Colombia.
Table 3 Key indicators of financial inclusion
| Indicator | 2014 | 2017 | 2018 |
| Access to formal financial services4* | 67% | 77% | 81.4% |
| Access to a cellular phone (% age 15+)** | 83.5% | - | |
| Internet access (% age 15+)** | 59.8% | - | |
| Persons with an account (% age 15+)** | 38.9% | 45.7% | - |
| Persons with an active account (% age 15+)** | 29.7% | 37.6% | - |
| Access points per 1000 k25*** | 122.8 | 134 | 167 |
| Number of access points | 446 521 | 532 138 | 581 747 |
Source: created by the authors
*Financial Inclusion Demand Surveys
**G-20 Core Set of Financial Inclusion Indicators, World Bank
***Financial Inclusion Report 2018
As can be seen in the table, a substantial increase in these indicators occurred from 2014 to 2017. Nevertheless, many challenges remain to be met in terms of financial inclusion. As stated in the latest Financial Inclusion Report of the Financial Superintendency of Colombia and Banca de las Oportunidades, there is an urgent need to close the urban-rural gap by strengthening the non-bank correspondent and designing products suited to the needs of farmers. The inclusion indicator for 2018 in cities and urban areas was around 89% and 55% for dispersed rural municipalities (Banca de las Oportunidades & Superintendencia Financiera de Colombia, 2018). In addition, risk protection products should be promoted to mitigate their effects on the household economy, and the digitalization of financial services should be consolidated. In line with these objectives, the National Development Plan 2018-2022 has as its goals to increase the financial inclusion indicator to 85%, measured as the ratio of adults with some financial product over the adult population projected by DANE, and to increase the indicator of adults with active products to 77%.
Descriptive statistics
The descriptive statistics of the variables used to estimate the econometric models are shown below. As seen in Table 4, approximately 48% of the surveyed population are women; households comprise an average of 3 people; the average age is 46 years; 65% are in strata 1 and 2. In addition, 41% of people have a university education, and 57% own their home. The main economic activity of those who responded to the survey was to be working. Fourteen % have a business or company, and only 18% of respondents claim to have some form of savings. Finally, over 50% of the surveyed population had an income in the last month below COP 1 000 000, and the population is concentrated in urban areas (81%).
Table 4 Descriptive statistics of the model variables
| Variable | Abbreviation | Mean | Standard deviation | Min. | Max. |
| Number of people in the household | IDE1 | 3.665951 | 1.775066 | 1 | 23 |
| Gender (1: male, 0:Female) | A2 | 0.4231595 | 0.4940982 | 0 | 1 |
| Age | A3 | 46.83236 | 15.72775 | 18 | 90 |
| Type of Dwelling (1: House, 0: Apartment or other) | B1 | 0.8118098 | 0.3908939 | 0 | 1 |
| Stratum | Stratum | ||||
| 1 | 0.24616564 | 0.43077618 | 0 | 1 | |
| 2 | 0.4150307 | 0.4927651 | 0 | 1 | |
| 3 | 0.2661043 | 0.4419533 | 0 | 1 | |
| 4 | 0.0464724 | 0.210522 | 0 | 1 | |
| 5 | 0.0217791 | 0.1459729 | 0 | 1 | |
| 6 | 0.001227 | 0.0350097 | 0 | 1 | |
| Type of dwelling (1: owned, 0: leased) | C1 | 0.5779141 | 0.49393 | 0 | 1 |
| Owns business/company (1:Yes, 0: No) | C8 | 0.1389571 | 0.3459282 | 0 | 1 |
| Has Savings (1: YES, 0: No) | D1 | 0.1800613 | 0.384268 | 0 | 1 |
| Has credits (1: Yes, 0: No) | D4 | 0.2631902 | 0.4403985 | 0 | 1 |
| Educational Level | N1 | ||||
| N12 (primary) | 0.9423313 | 1.158038 | 0 | 13 | |
| N13 (Secondary) | 1.442485 | 1.36129 | 0 | 15 | |
| N14 (Technical/Technological) | 0.470092 | 0.7940344 | 0 | 8 | |
| N15 (University) | 0.4093558 | 0.844428 | 0 | 16 | |
| N16 (Postgraduate) | 0.0470859 | 0.2852794 | 0 | 6 | |
| Economic activity | Activity | ||||
| 1. Working | 0.55398773 | 0.49707678 | 0 | 1 | |
| 2. Working and studying | 0.03496933 | 0.18370213 | 0 | 1 | |
| 3. Retired | 0.06134969 | 0.23997064 | 0 | 1 | |
| 4. Looking for a job | 0.06134969 | 0.23997064 | 0 | 1 | |
| 5. Studying | 0.01027607 | 0.10084878 | 0 | 1 | |
| 6. Household trades | 0.24953988 | 0.43274672 | 0 | 1 | |
| 8. Permanently disabled for work | 0.01533742 | 0.12289095 | 0 | 1 | |
| 89. Other activity | 0.01319018 | 0.11408858 | 0 | 1 | |
| Last month's income | Income | ||||
| 1. Less than COP 500 000 | 0.2154908 | 0.4111624 | 0 | 1 | |
| 2. From COP 500 000 to less than COP 1 000 000 | 0.3680982 | 0.48228821 | 0 | 1 | |
| 3. From COP 1 000 000 to less than COP 1 500 000 | 0.1842025 | 0.38764925 | 0 | 1 | |
| 4. From COP 1 500 000 to less than COP 2 000 000 | 0.0946319 | 0.29270583 | 0 | 1 | |
| 5. From COP 2 000 000 to less than COP 3 000 000 | 0.048773 | 0.21539312 | 0 | 1 | |
| 6. From COP 3 000 000 to less than COP 4 000 000 | 0.0174847 | 0.13106863 | 0 | 1 | |
| 7. From COP 4 000 000 and more | 0.0124233 | 0.11076534 | 0 | 1 | |
| 99. Do not know, No answer | 0.0588957 | 0.23542939 | 0 | 1 | |
| Rurality (1. Urban. 0. Rural) | rural | 0.8105828 | 0.3918697 | 0 | 1 |
Source: created by the authors, 2019
Results
LPM, logit and probit models were estimated to determine the factors influencing the probability of acquiring compulsory or induced insurance6. STATA/MP 14.1 software was used to perform the model estimations. Using the stepwise command, the backward tests were performed to select the best model, using a selection probability of 0.1. The estimation results are shown in Table 5.
Table 5 Model estimates
| Variable | LPM | LOGIT | PROBIT |
| IDE1 | 0.03526*** | 0.04208*** | 0.04096*** |
| A2 | 0.04513*** | 0.05431*** | 0.05177*** |
| A3 | 0.00608*** | 0.01024*** | 0.00941*** |
| A3_2 | -0.0000*** | -0.0001** | -0.0001** |
| income_2 | 0.06302*** | 0.08801*** | 0.08316*** |
| income_3 | 0.15013*** | 0.17711 | 0.17268 |
| income_4 | 0.16010*** | 0.18525 | 0.18049 |
| income_5 | 0.22190*** | 0.25893*** | 0.25228*** |
| income_6 | 0.27687*** | 0.36284 | 0.35197 |
| income_7 | 0.18589*** | 0.22479 | 0.19749 |
| stratum_2 | 0.10410*** | 0.12940 | 0.12517 |
| stratum_3 | 0.11066*** | 0.13751*** | 0.13508*** |
| stratum_4 | 0.11218*** | 0.13182*** | 0.13185*** |
| stratum_5 | 0.34683*** | 0.48236*** | 0.43431*** |
| stratum_6 | 0.34078** | 0.48855** | 0.48275** |
| stratum_7 | 0.23607** | 0.27823** | 0.27819** |
| C1 | 0.04231*** | 0.05015*** | 0.04941*** |
| C8 | 0.04520*** | 0.05344*** | 0.05083*** |
| D1 | 0.04513*** | 0.04948*** | 0.04779*** |
| D4 | 0.20796*** | 0.22737*** | 0.22270*** |
| N12 | -0.0190*** | -0.0215*** | -0.0210*** |
| N13 | -0.0167*** | -0.0183** | -0.0179** |
| N14 | 0.02658*** | 0.02940** | 0.02652** |
| rural | -0.0482*** | -0.0615*** | -0.0567*** |
| N16 | 0.07707*** | 0.11150*** | 0.10546*** |
| activity_2 | 0.08406*** | 0.09517*** | 0.09412*** |
| activity_3 | 0.01267 | 0.04048 | 0.03173 |
| activity_4 | -0.0225 | -0.0255 | -0.0199 |
| activity_5 | 0.18074*** | 0.20815*** | 0.20194*** |
| activity_6 | -0.0137 | -0.0145 | -0.0149 |
| activity_7 | -0.0478 | -0.1040 | -0.1031 |
| activity_8 | -0.0132 | -0.0129 | -0.0094 |
| _cons | 0.00864 | -0.6310*** | -0.6069*** |
| R2/Pseudo R2 | 0.184 | 0.1494 | 0.1487 |
| R2_adj/Log_likelihood | 0.18 | -3 733.008 | -3 735.9461 |
| N | 6 520 | 6 520 | 6 520 |
Source: created by the authors, 2019
Individual significance in asterisks: ***<0.01, **<0.05 y *<0.1.
As can be seen, most of the variables are statistically significant, partly because the backward-selection method was used to determine the best model specification. Only some of the non-significant discrete variables concerning the same variable were retained in this version of the model (for the economic activity variable).
Another point to highlight is that the signs of the variables are robust regardless of the model used, and the signs of the coefficients are consistent with those expected and the findings of other authors, except in the case of the rurality variable. For all the estimated models, the variable has a negative and significant sign, indicating that people located in rural areas have a higher probability of accessing mandatory or induced insurance (approximately 4.82%). This result can be explained by the fact that the variable is highly unbalanced in the sample in favor of urban residents, as seen in Table 6.
Table 6 Mandatory/induced insurance holdings vs. rurality
| Mandatory/induced insurance | ||||
| Rurality | 0 | 1 | Total | |
| 2. Intermediate. | 0 | 792 | 443 | 1 235 |
| 3. Rural. | ||||
| 4. Dispersed rural | ||||
| 1. Cities and urban areas | 1 | 3 119 | 2 166 | 5 285 |
| Total | 3 911 | 2 609 | 6 520 | |
Source: created by the authors, 2019
Thus, the variables that show a positive relation with the probability of acquiring mandatory or induced insurance are the number of household members (3.53%), age, the economic activities "working and studying" (8.4%) and "retired" (1. 27%), stratum (incrementally for higher stratum), owning a house (4.23%), owning a business (4.52%), having savings (4.51%), having credit (20.8%), having university or graduate education levels, and income (incrementally for higher income). In line with the studies by Iregui-Bohórquez et al. (2016) and Sanderson et al. (2018), a positive but non-linear relation between access to insurance with age is found, i.e., there comes a point where interest in financial services is lost since an increase in one year of age increases the probability by 0.61%, but each time it does so at a decreasing rate of 0.00987%. In addition, it is found that men are 4.51% more likely to have access to insurance than women. For this gender variable, there is no consensus on its influence on access to financial products. In the case of Murcia-Pabón (2007), gender was not found to be a significant variable in access to credit cards, but it was for access to a mortgage loan. On the other hand, Pacheco and Yaruro (2016) find that gender and age are not related to not holding financial products, despite their knowledge. Likewise, Gómez et al. (2016) find that gender, age, and residence region do not affect the demand for deposit accounts. The variables that show a negative sign for the probability of obtaining insurance are primary (-1.9%) and secondary (-1.7%) education levels and the rurality variable discussed in previous paragraphs.
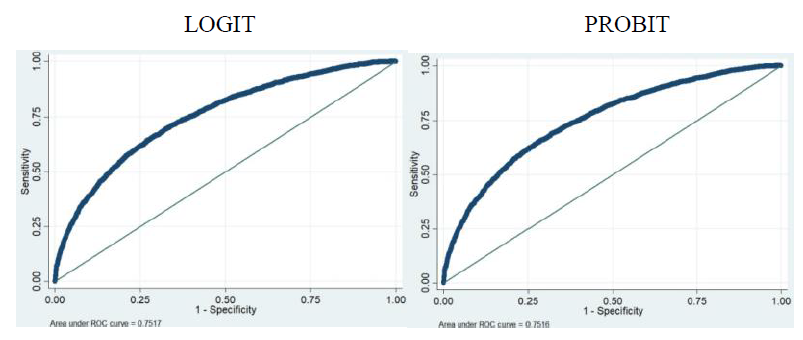
It is well known that the pseudo R-squared in a logit or probit model is not interpreted similarly to one from a least squares regression. So, to determine how well the above models (especially the logit and probit) fit, the classification tables were adjusted (Table 7), some statistics such as sensitivity and specificity were calculated (Table 8), and their corresponding ROC curves were plotted (Figure 1).
Table 7 Logit and probit models classification tables
| Real value of Y | |||||||
| LOGIT | PROBIT | ||||||
| 1 | 0 | Total | 1 | 0 | Total | ||
| Adjusted value of Y | 1 | 1 324 | 646 | 1 970 | 1 314 | 639 | 1 953 |
| 0 | 1 285 | 3 265 | 4 550 | 1 295 | 3 272 | 4 567 | |
| Total | 2 609 | 3 911 | 6 520 | 2 609 | 3 911 | 6 520 | |
Source: created by the authors, 2019
Table 8 Sensitivity, specificity, and classified correctness rate of logit and probit models
| LOGIT | PROBIT | |
| Sensitivity | 50.75% | 50.36% |
| Specificity | 83.48% | 83.66% |
| Positive predictive value | 67.21% | 67.28% |
| Negative predictive value | 71.76% | 71.64% |
| False + rate for true ~D | 16.52% | 16.34% |
| False - rate for true D | 49.25% | 49.64% |
| False + rate for classified | 32.79% | 32.72% |
| False - rate for classified | 28.24% | 28.36% |
| Correctly classified | 70.38% | 70.34% |
Source: created by the authors, 2019
Note 1:=D and 0=~D
The table above shows that the total number of individuals correctly classified were (1 324+3 265)/6 520=70.38% for the logit model and (1 314+3 272)/6 520=70.34% for the probit model. In other words, the logit model manages to classify individuals better, especially those who do not have compulsory or induced insurance.
Table 8 indicates that the optimal values for sensitivity and specificity are 50.75% and 83.48% for the logit model, respectively, and 50.36% and 83.66% for the probit model, respectively. Sensitivity is the true positive rate, and specificity is the true negative rate. Therefore, the result indicates that the logit classifies slightly better for true ones, while the probit does better for true negatives. Nevertheless, as indicated above, the logit performs a better classification of individuals.
Finally, Figure 1 shows the logit and probit models' ROC (Receiver Operating Characteristics) curves. These curves show the model fit for different cut-off points and their corresponding combinations of Sensitivity and 1-specificity. According to Hosmer and Lemeshow (1991), the area under the ROC curve (AUC) determines the predictive power of logit and probit models; if the area under the curve is equal to 0.5, it is said that there is no discriminatory power (it would be like flipping a coin), if it is between 0.5 and 0.7, discrimination is poor, if it is between 0.7 and 0.8, it is acceptable, between 0.8 and 0.9 it is excellent, and greater than 0.9 it is exceptional. In this case, there is an AUC of 0.7517 for the logit and 0.7516 for the probit, so the classification power of these models is acceptable.
Conclusions
Inclusive insurance is an essential tool for strengthening the financial resilience of individuals, households, and businesses, as it enables them to cope with the financial impacts of any shocks while protecting them from entering or returning to poverty. Together, this improves the welfare of society and increases economic growth. Nevertheless, its importance has only recently been understood, and only now has the focus of policymakers turned to this financial product as a sign of real progress in managing financial inclusion indicators.
Colombia's progress in terms of financial inclusion has been positive and evidenced in many aspects. For example, ranking first in the 2018 Global Microscope as the country with the best regulatory and institutional environment for financial inclusion within a sample of 55 countries represents significant progress. In addition, through the National Development Plan 2014-2018, it was possible to increase the proportion of adults with access to a financial product from 72% to 84%, with active savings accounts from 53% to 65% and a reduction in the use of cash, from 11.5% to 8.5% (The Economist, 2018). In addition to these advances, the three financial inclusion surveys conducted in the country represent a substantial effort at a national level to understand the behavior of Colombians in terms of access to and use of financial products, to provide a complete picture of the progress, challenges, and opportunities for strengthening the financial sector. In addition, it is sought to provide information to the government and financial institutions for the design of public policies and the supply of financial services tailored to the characteristics and needs of the demand.
The objective of this article is to make use of this valuable information contained in the insurance demand survey, and to provide empirical evidence on the determinants of access to insurance, motivated by the fact that only 15% of the people surveyed have ever had insurance, only 18% have had life insurance, 2% have acquired unemployment insurance, and less than 1% have had agricultural insurance. In other words, the insurance market has a low penetration level and a great opportunity to expand.
The results show that the coefficients of the model variables are consistent with those expected and the findings of other authors. Additionally, the estimation of the three econometric models (LPM, logit, and probit) confirmed the robustness of the following results. Thus, the probability of acquiring compulsory or induced insurance increases with the number of household members, age, the economic activities "working and studying" and "studying," socioeconomic stratum, income, owning a home or business, having savings, having credit, and having university or postgraduate education levels. Accordingly, achieving significant progress in the promotion of this financial product must first focus on policy strategies such as financial education, as well as on the design of insurance products in line with the characteristics of the demanders, which achieve not only access to this type of financial services but also for their use, the promotion of digital payments, and the design of financial education strategies. Future work could investigate the supply factors influencing access to this type of financial services. Likewise, the sequence of access to financial products can be investigated, i.e., how individuals order the acquisition of financial products. The sample of individuals can also be monitored to identify the dynamics of the decision to access or not to access some type of insurance, i.e., how the decision to access changes over time and the main determinants of this change.
REFERENCES
Ahamed, M. M., & Mallick, S. K. (2019). Is financial inclusion good for bank stability? International evidence. Journal of Economic Behavior and Organization, 157, 403-427. https://doi.org/10.1016/j.jebo.2017.07.027 [ Links ]
Altunbaş, Y., Thornton, J., & Kara, A. (2010). What Determines Financial Exclusion? Evidence from Bolivian Household Data. 44(0), 11. [ Links ]
Anaya, A., Buelvas, J., & Romero, Y. (2020). Pobreza e inclusión financiera en el municipio de Montería, Colombia. Revista de Ciencias Sociales, 26(1), 144-160. https://doi.org/10.31876/rcs.v26i1.31315 [ Links ]
Banca de las Oportunidades, Superfinanciera, & Fasecolda. (2018). Estudio de demanda de seguros 2018 (p. 96). [ Links ]
Banca de las Oportunidades, & Superintendencia Financiera de Colombia. (2018). Reporte de inclusión financiera 2018. [ Links ]
Banca de las Oportunidades, Superintendencia Financiera, & Fasecolda. (2018). Estudio de demanda de seguros 2018. [ Links ]
Boitano, G., & Abanto, D. F. (2020). Challenges of financial inclusion policies in Peru. Revista Finanzas y Politica Economica, 12(1), 89-117. https://doi.org/10.14718/REVFINANZPOLITECON.V12.N1.2020.3177 [ Links ]
Cano, C., Esguerra, P., García, N., Rueda, L., & Velasco, A. (2013). Acceso a servicios financieros en Colombia. [ Links ]
Devlin, J. F. (2005). A detailed study of financial exclusion in the UK. Journal of Consumer Policy, 28(1), 75-108. https://doi.org/10.1007/s10603-004-7313-y [ Links ]
Dorn, M., Sharpe, D., Dickey, G., & Herring, D. (2017). Understanding the Determinants of a Long-Term Care Insurance Purchase. Journal of Financial, November. [ Links ]
Dunham, I. M. (2019). Landscapes of financial exclusion: Alternative financial service providers and the dual financial service delivery system. Business and Society Review, 124(3), 365-383. https://doi.org/10.1111/ basr.12180 [ Links ]
Estrada, D., & Zamora, P. (2017). Ensayos sobre Inclusión financiera en Colombia. [ Links ]
Fowowe, B. (2020). The effects of financial inclusion on agricultural productivity in Nigeria. Journal of Economics and Development, ahead-of-p(ahead-of-print), 6-14. https://doi.org/10.1108/jed-11-2019-0059 [ Links ]
Gómez, J. E., Jaramillo, J., & Meisel, A. (2016). Uso de efectivo y tarjetas débito y crédito en Colombia. Borradores de Economía, No. 950. 2016. [ Links ]
Hosmer, D. W. J., & Lemeshow, S. L. (1991). Applied Logistic Regression. [ Links ]
Iregui-Bohórquez, A. M., Melo-Becerra, L. A., Ramírez-Giraldo, M. T., & Tribín-Uribe, A. M. (2016). Determinantes del acceso al crédito formal e informal : evidencia de los hogares de ingresos medios y bajos en Colombia. Borradores de Economía; No. 956. http://repositorio.banrep.gov.co/handle/20.500.12134/6267 [ Links ]
Martinez, L. B., Scherger, V., Guercio, M. B., & Orazi, S. (2020). Evolution of financial inclusion in Latin America: Management area: Business Economics. Academia Revista Latinoamericana de Administracion, 33(2), 261-276. https://doi.org/10.1108/ARLA-12-2018-0287 [ Links ]
Murcia-Pabón, A. (2007). Determinantes del acceso al crédito de los hogares colombianos. Banco de La Republica, 449(4), 54. [ Links ]
Pacheco, D. J., & Yaruro, A. M. (2016). Factores que afectan la tenencia de productos financieros en Colombia. Borradores de Economía; No. 978, 17-38. [ Links ]
Raichoudhury, A. (2020). Major Determinants of Financial Inclusion: State-Level Evidences from India. Vision, 24(2), 151-159, https://doi.org/10.1177/0972262920923882 [ Links ]
Rodriguez, D., & González, G. (2017). Principios de econometría (F. E. ITM (ed.)). [ Links ]
Rodríguez, S., & Riaño, F. (2016). Determinantes del acceso a los productos financieros en los hogares colombianos. Estudios Gerenciales, 32, 14-24. https://doi.org/10.1016/j.estger.2015.11.004 [ Links ]
Salignac, F., Marjolin, A., Reeve, R., & Muir, K. (2019). Conceptualizing and Measuring Financial Resilience: A Multidimensional Framework. Social Indicators Research, 145(1), 17-38. https://doi.org/10.1007/s11205-01902100-4 [ Links ]
Sanderson, Abel; Learnmore, Mutandwa; Pierre Le, R. (2018). A Review of Determinants of Financial Inclusion. International Journal of Economics and Financial Issues, 8(3), 1-8. [ Links ]
Simpson, W., & Buckland, J. (2009). Examining evidence of financial and credit exclusion in Canada from 1999 to 2005. Journal of Socio-Economics, 38(6), 966-976, https://doi.org/10.1016/j.socec.2009.06.004 [ Links ]
Superintendencia Financiera, & Banca de las Oportunidades. (2017). Estudio de demanda de inclusión financiera. [ Links ]
The Economist. (2018). Microscopio global de 2018. The Economist Intelligence Unit, 91. [ Links ]
Tuesta, D., Peña, X., & Hoyo, C. (2014). Determinants of financial inclusion in Mexico based on the 2012 National Financial Inclusion Survey (ENIF). January. [ Links ]
Tuesta, D., Sorensen, G., Haring, A., & Cámara, N. (2015). Inclusión financiera y sus determinantes: el caso argentino. BBVA Research, 8(7), 28. [ Links ]
Wokabi, V. W., & Fatoki, O. I. (2019). Determinants of Financial Inclusion in East Africa. International Journal of Business and Management, VII(1). https://doi.org/10.20472/bm.2019.7.1.009 [ Links ]
Zins, A., & Weill, L. (2016). The determinants of financial inclusion in Africa. Review of Development Finance, 6(1), 46-57. https://doi.org/10.1016/j.rdf.2016.05.001 [ Links ]
1There are many other definitions provided in the literature. For example, Simpson and Buckland (2009) define financial exclusion as not having access to any formal financial product, whether payment, savings, or credit. On the other hand, Cano et al. (2013) use three concepts to define exclusion: first, as the lack of access to a bank account; second, as the absence of a credit card; and third, as the use of informal financial alternatives.
2There are many other definitions provided in the literature. For example, Simpson and Buckland (2009) define financial exclusion as not having access to any formal financial product, whether payment, savings, or credit. On the other hand, Cano et al. (2013) use three concepts to define exclusion: first, as the lack of access to a bank account; second, as the absence of a credit card; and third, as the use of informal financial alternatives.
3The database is available at the following link: http://bancadelasoportunidades.gov.co/es/publicaciones/encuestas-de-demanda
6For more information on these models, see Chapter 4 of Rodriguez and Gonzalez (2017).
Received: March 30, 2020; Accepted: April 29, 2021; Published: May 01, 2021
 Este es un artículo publicado en acceso abierto bajo una licencia Creative Commons
